
The Christmas bike you choose matters, but so does the way you pay for it. A Bike to Work bike for Christmas may qualify under Ireland’s scheme if it’s new, used mainly for qualifying journeys and arranged through a participating employer. The limit is €1,250 for other bikes, €1,500 for electric bikes and €3,000 for cargo bikes, including accessories and related products.
It’s easy to focus on the bike itself and overlook the scheme rules that shape the purchase. The employer pays for the bike, and you repay the cost through salary deductions; you can use the scheme once in a four-year period.
This guide explains how the limits and payroll deductions work, which bicycles and accessories may qualify, and what to understand about VAT when arranging a Christmas purchase. You’ll have a clearer picture of the steps involved and how to plan for a bike that suits your commute.
Key Takeaways
- Match your bike type to the scheme limit: €1,250 for other bikes, €1,500 for electric bikes or €3,000 for cargo bikes, including accessories.
- Understand how your employer arranges payment and salary deductions, and how the four-year interval affects when you can use the scheme again.
- Check whether the bike and equipment fit the eligibility rules, including the requirement for a new bicycle used mainly for qualifying work journeys.
- See how the purchase process and VAT treatment affect your Christmas plans before settling on a bike and accessories.
How much can I spend on the Bike to Work Scheme, and how often can I use it?
In Ireland, the scheme limit depends on the bicycle type and includes accessories and related products. It is €1,250 for other bikes, €1,500 for electric bikes and €3,000 for cargo bikes. An employee can use the scheme once in a four-year period, counted by tax year. A Bike to Work bike for Christmas must be new and used mainly for journeys between home and the normal workplace.
You can time a scheme purchase for Christmas, but the bike must be for your own use and qualifying work journeys. It cannot be bought as a gift for someone else. A partner or family member cannot use your scheme purchase to buy a bike for another person.
If your employer provides a bike tax-free, the bike and safety equipment must stay within the scheme limit. Eligible safety equipment counts towards that amount, so include it in your purchase plan. PAYE employees can apply if their employer offers the scheme. Self-employed people cannot use it, and the employer must set up the scheme.
Savings depend on the employee’s tax band and employer arrangement. Estimated savings range from 31% to 52% on the bike and accessories. Repayments are taken from gross salary and are generally spread over 12 months. Depending on salary arrangements, deductions may be weekly, fortnightly or monthly.
Choose a suitable bike and request a quotation for your employer’s scheme application. Your employer arranges payment to the retailer, and you repay the cost through salary deductions. If you leave your job before the payback period ends, you may need to repay the outstanding balance. For a Bike to Work bike for Christmas, start early: employer approval and the retailer’s order process are separate steps.
Cycle2Work scheme savings and payroll deductions
Your net cost depends on your tax position and the payroll arrangement with your employer. Review the proposed deductions alongside the bike quotation so you can plan the purchase based on your own circumstances, rather than a headline saving.
Salary sacrifice and payroll deductions
Under salary sacrifice, your employer pays the supplier and the cost is repaid from your gross salary. Deductions may be weekly, fortnightly or monthly, depending on your salary arrangements. Review the proposed schedule before approval to see how it fits your regular pay.
For a Bike to Work bike for Christmas, include the bike and eligible safety equipment in the quotation. Your employer uses it to arrange payment, and payroll applies the agreed deductions. The employer pays the supplier directly: you do not buy the bike first and claim reimbursement afterwards.
Tax, PRSI and USC savings
Salary-sacrifice repayments are deducted without tax, PRSI or USC being charged on those repayments. The estimated saving varies with the employee’s tax band: a €1,200 purchase example gives an estimated €288 saving at a 20% tax rate, or €624 at a 40% tax rate. These figures illustrate why the same purchase can produce different outcomes.
The arrangement also affects the employer, with an estimated PRSI saving of 10.75%. For your own planning, focus on the amount financed and your tax position. A Christmas bike purchase through the scheme should fit both your commute and the payroll deduction you are comfortable with.
Using a savings calculator
A savings calculator can provide an estimate of the difference between the purchase amount and your likely net cost. Enter the bike total, eligible safety equipment and relevant tax details to see how the estimate changes. Treat the result as a planning aid, not a replacement for your employer’s payroll schedule.
Compare the calculator result with the quotation before submitting your application. This helps you discuss the proposed purchase and deductions with your employer using clear figures. To explore options for a scheme purchase, view the Cycle to Work scheme purchase options.

Eligible bicycles and pedelecs
Ireland’s Cycle to Work Scheme covers new bicycles and pedelecs. A pedelec is electrically assisted but still requires some effort from the cyclist, so it differs from a motorbike, scooter or moped, which the scheme excludes. The bicycle and safety equipment must be used mainly for journeys between home and the employee’s normal workplace. A qualifying journey can also include cycling to a train station as part of the commute.
Second-hand bicycles and equipment do not qualify. The scheme is intended for cycling, not simply for buying a bike for leisure or giving one to another person. Choose a new bicycle that suits the journey it will be used for, whether that means commuting directly or cycling to public transport. The requirement for the employee to use the bike mainly for qualifying work journeys applies to adult bikes as well as other eligible bicycles.
Safety equipment and certain cycling accessories can be included with the bike. Eligible examples include:
- Helmets that conform to European standard EN 1078.
- Lights and locks for visibility and security.
- Panniers and mudguards for carrying items and riding in wet conditions.
Eligible safety equipment counts towards the scheme’s maximum tax-free value, so include it when planning the total. Keep the purchase focused on the bike and qualifying safety equipment.
Cargo bikes are eligible too. Section 8 of Ireland’s Finance Bill 2022 defines a cargo bicycle by its special-purpose frame, designed to carry large or heavy loads, or passengers other than the rider. It must use a container or platform integrated into or affixed to the frame. Cargo bikes became eligible to apply for through the scheme from 1 January 2023.
For a Christmas purchase, first decide which type of bike suits your commute, then consider the safety equipment you need. Include both in your proposed purchase so the quotation reflects the items you plan to buy through the scheme.
Tax-free bicycle scheme and VAT requirements
In Ireland, the Ride to Work Scheme combines an employer-paid purchase with salary deductions. The quotation and invoice should make the full purchase amount clear, including any eligible safety equipment.
How the tax-free scheme works
A participating employer pays the supplier for a new bicycle and eligible equipment. The employee repays the cost through salary deductions, rather than paying first and seeking reimbursement. That distinction matters: the tax exemption does not apply when an employee buys the bicycle and is later reimbursed by the employer.
For VAT records, the supplier’s quotation and invoice should show the purchase total and any VAT charged. Use that total when the employer arranges payment and compares the purchase with the scheme limit. The scheme’s tax treatment concerns the employer-provided bicycle arrangement; it should not be treated as a separate VAT refund for the employee.
The scheme is for PAYE employees whose employers offer it, not self-employed people. Your employer must set up the scheme, and you agree that the bike is for your own use on qualifying work journeys.
Scheme spending limits
The Irish limits include the bicycle, accessories and related products: €1,250 for other bikes, €1,500 for electric bikes and €3,000 for cargo bikes. These limits apply whether the purchase is described as the Cycle to Work Scheme or Bike to Work Scheme. The bicycle type determines which ceiling applies.
If the chosen bicycle and equipment cost more than the relevant limit, the employee can pay the excess directly. For example, a €2,000 electric bike could involve a €500 employee contribution against the €1,500 scheme limit. Keep the employer’s payment and any personal contribution distinct in the purchase arrangement.
Before approval, compare the supplier’s full quotation with the applicable ceiling, including accessories and VAT shown in the total. Explore eligible bicycle options to help shape a quotation that fits the scheme arrangement.
Cyclecentre.com
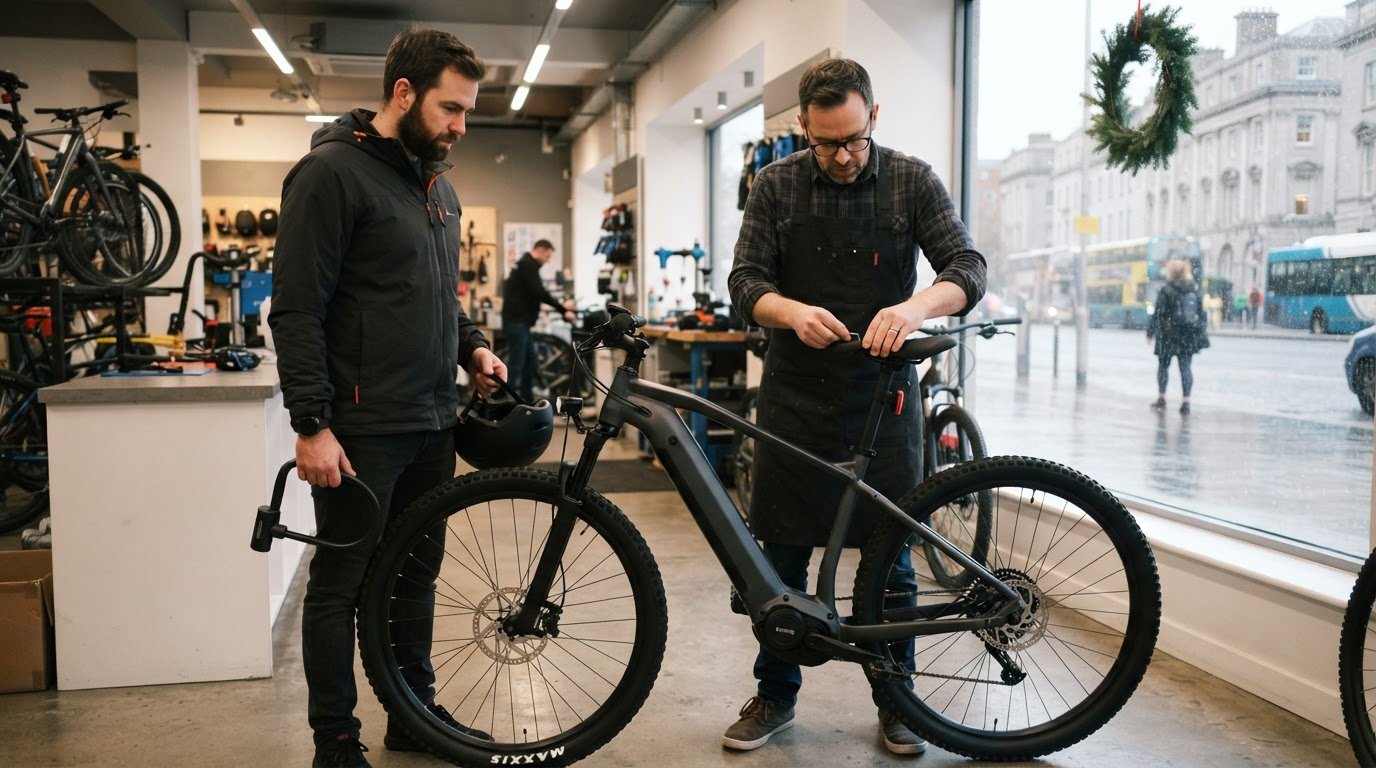
Once you understand the Irish scheme limit and employer approval process, Cyclecentre.com can help you choose a suitable bike. It offers Bike to Work scheme quotes through an online application, with no obligation. Compare bikes for your commute and include eligible safety equipment in the proposed purchase.
The right bike depends on your route and riding needs. A road performance bike may suit road commuting, while an electric mountain bike is designed for a different style of riding. Cyclecentre.com offers road, gravel, adventure and electric bikes to help you find a suitable option. Keep your employer’s quotation and approval process in mind as you plan.
For guidance on a suitable bike for your scheme purchase, contact Cyclecentre.com.
Choose a bike for qualifying journeys
A Bike to Work bike can support regular journeys as well as leisure rides. Before choosing a model, consider the journeys you plan to make, including the roads or paths you use, what you need to carry and the type of ride you prefer. These details can help you identify a bike suited to your needs and the journeys you intend to make.
Take time to assess how you will use the bike and use that information to guide your purchase. A clear idea of your requirements can help you choose a suitable model and prepare a focused scheme quotation.
Ask Cyclecentre.com about your bike to discuss your options for qualifying journeys.
Frequently Asked Questions
How does it work?
In Ireland, choose a new bike for your own qualifying work journeys and get a quotation for your employer’s scheme application. Your employer arranges payment, and you repay the cost through salary deductions. For a Christmas purchase, allow time for employer approval and the retailer’s order process. Plan around both before choosing a preferred delivery date.
What equipment does the scheme apply to?
The scheme can cover a new bicycle or eligible pedelec, together with qualifying safety equipment and accessories. Examples include lights, locks, panniers and mudguards. A helmet must conform to European standard EN 1078. Include the equipment you need in the purchase quotation, and keep the selection relevant to cycling and safe use on qualifying journeys.
How much can I save?
Cyclecentre.com advertises savings of up to 52% through the scheme. Your individual saving depends on your tax position and the amount financed through salary sacrifice, so the advertised maximum is not a guaranteed personal result. A savings calculator can help illustrate how your tax band affects the estimate before you settle on a bicycle and accessories.
Do I own the bike straight away?
Read your employer’s scheme and payroll documents to understand who owns the bike during repayments and when ownership transfers. Keep the paperwork accessible, particularly if your employment circumstances change before deductions are complete, as you may need to repay the outstanding balance.
Got questions about the scheme?
The Cycle Centre provides an online application for a no-obligation Ride to Work scheme quotation. Use it to set out your proposed bike purchase, then follow your employer’s application process. Whether you commute in Dublin, Dundalk, Drogheda or elsewhere in Ireland, consider the journeys the bike needs to suit and include eligible safety equipment in your proposed purchase.
How do I pay for the bicycle?
Your employer pays the supplier, then the agreed amount is deducted from your gross salary through payroll. Deductions may be weekly, fortnightly or monthly, depending on your salary arrangements. If the purchase exceeds the applicable scheme allowance, you can pay the excess directly. Keep the quotation, employer approval and payroll details together to make the payment arrangement clear.